Anthropic can rally below its $1.5 trillion IPO valuation
A lower market cap can accompany a share-price gain. Three Anthropic IPO markets show why the benchmark, share count and fundraising rules matter.
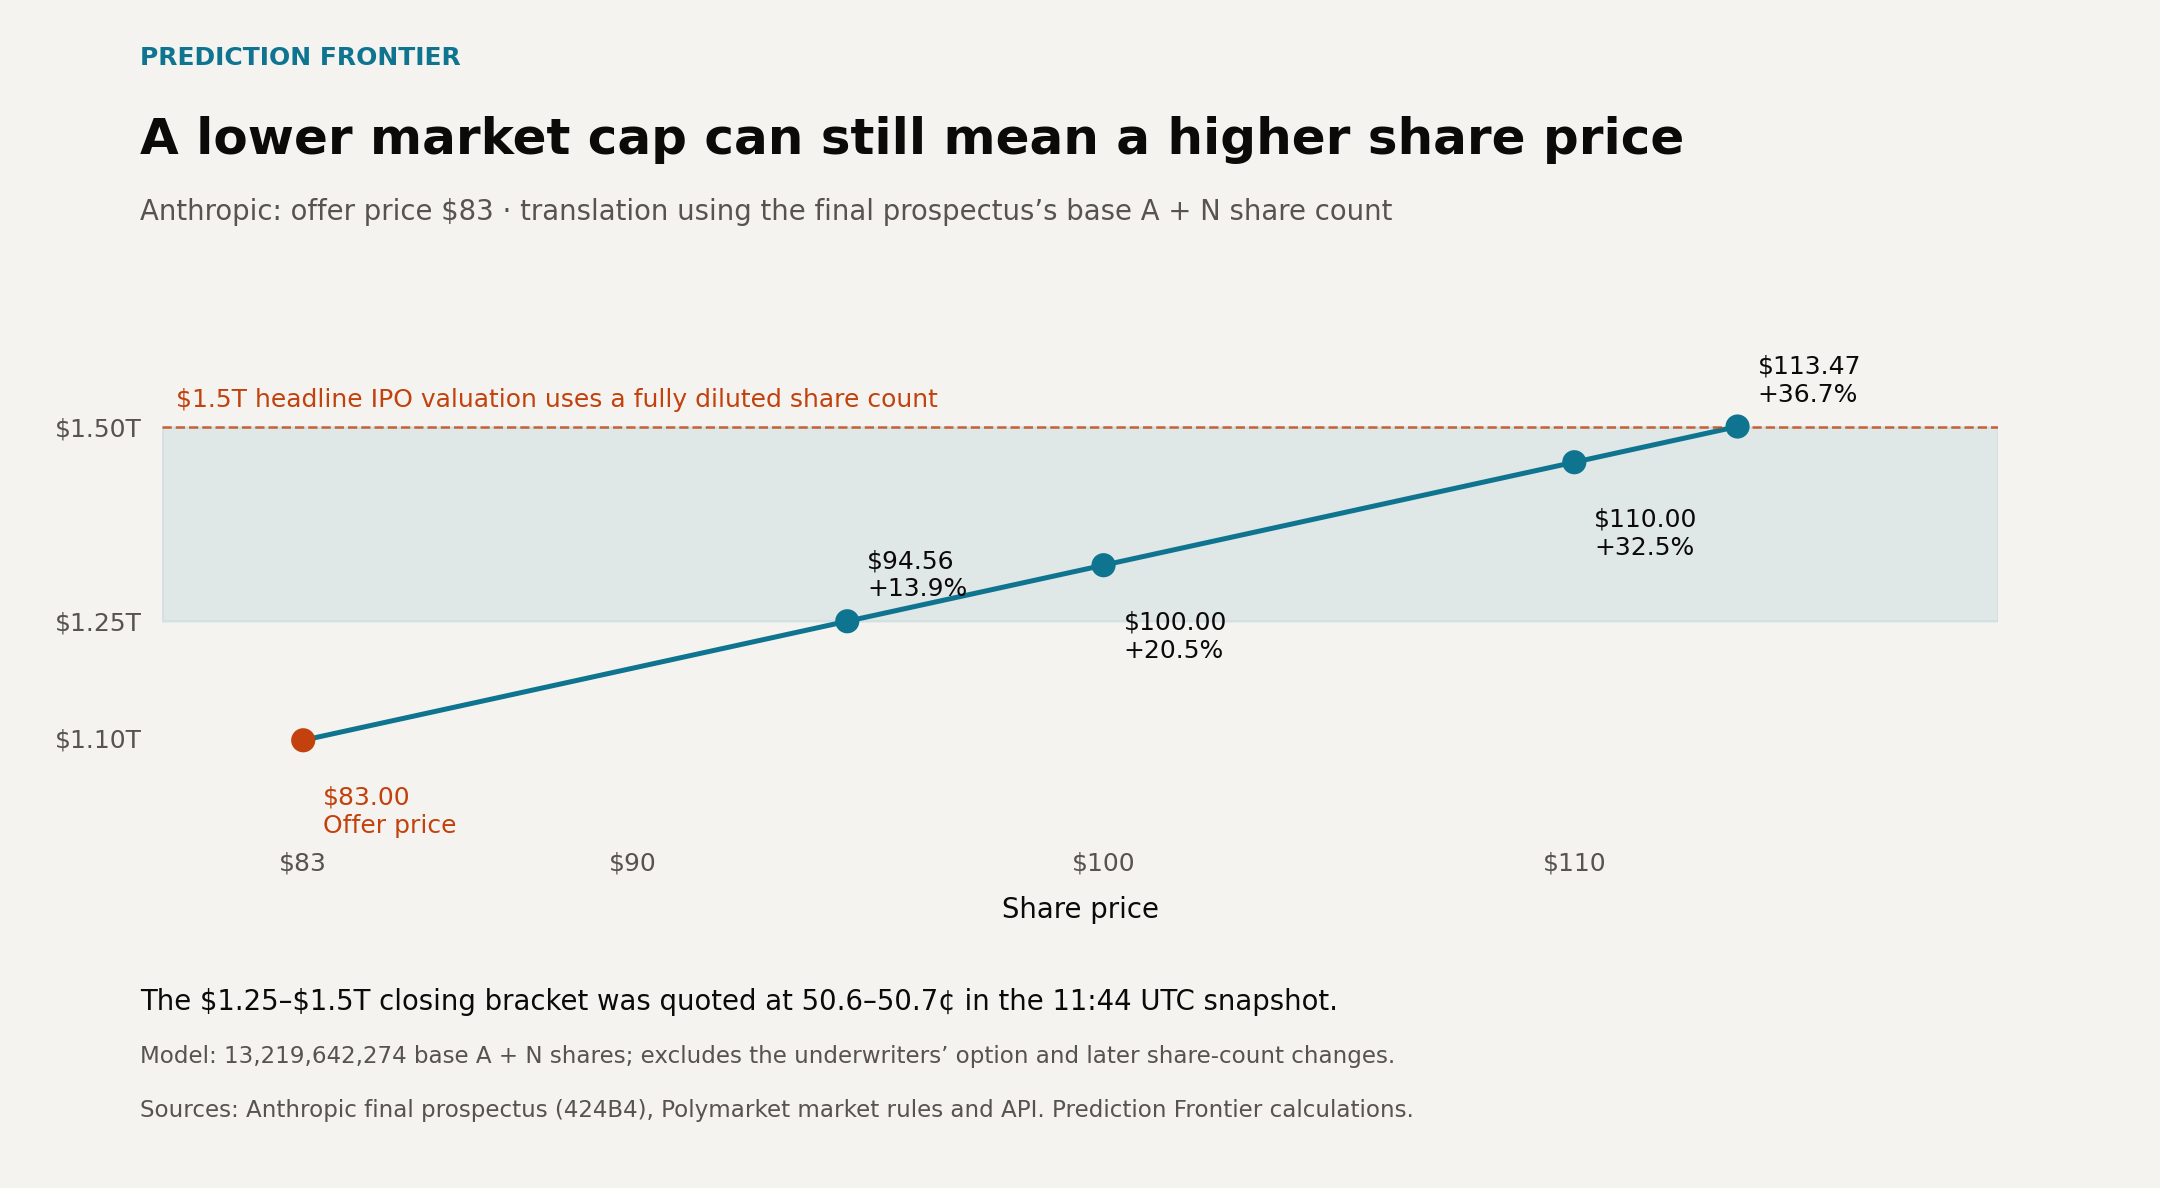
A $100 closing price would put Anthropic shares 20.5% above their $83 IPO offer price. On the base share count in its final prospectus, that would give the company a market capitalisation of about $1.32 trillion, below the $1.5 trillion valuation reported for the IPO. The apparent drop comes from comparing two different share counts.
That is the distinction behind the leading outcome in Polymarket’s first-day closing-market-cap event. Before the scheduled Nasdaq debut on 19 November, its $1.25–$1.5 trillion bracket had a 50.6–50.7¢ Yes quote in Prediction Frontier’s 11:44 UTC snapshot. Translating that range into share prices gives a different impression from comparing it with the IPO headline.
The share count changes the comparison
Anthropic priced its offering at $83 on 18 November. The approximately $1.5 trillion headline is a fully diluted valuation, which includes potential shares tied to instruments such as employee awards and convertible securities. The closing-market-cap contract defines its figure as shares outstanding multiplied by the first trading day’s closing price.
The final prospectus’s Offering section lists 7.583 billion Class A shares and 5.637 billion Class N shares after the base offering and concurrent private placement. Together, they give a base of about 13.22 billion economically participating shares, before the underwriters’ option. At $83, those shares imply a market capitalisation of approximately $1.10 trillion.
| Share price | Implied base market cap | Gain from $83 offer |
|---|---|---|
| $83.00 | $1.097 trillion | 0.0% |
| Approximately $94.56 | $1.250 trillion | 13.9% |
| $100.00 | $1.322 trillion | 20.5% |
| $110.00 | $1.454 trillion | 32.5% |
| Approximately $113.47 | $1.500 trillion | 36.7% |
On that denominator, the market’s preferred $1.25–$1.5 trillion closing range corresponds to roughly $94.56–$113.47 per share, or gains of about 14%–37% from the offer. A forecast below the fully diluted headline can therefore accommodate a sizeable first-day rise.
This is a translation of the stated base share count. The contract settles using the primary exchange’s reported figure, with a reliable-source fallback. Exercise of the underwriters’ option and other changes to actual shares outstanding can alter the final denominator.
The IPO gain starts at $83
Polymarket’s separate close-above-IPO-price contract had a 98.5–98.8¢ Yes quote at 11:44 UTC. It asks whether the first-day closing price will exceed the final offer price. The price of the first Nasdaq trade is a separate benchmark.
Carry the hypothetical $100 close forward. An investor allocated shares at $83 would have a gain of 20.5% before costs. Someone who bought at a hypothetical $105 opening trade and sold at that same close would lose 4.8%.
| Purchase price | Sale price | Return before costs |
|---|---|---|
| $83 IPO allocation | $100 | +20.5% |
| $105 opening purchase | $100 | −4.8% |
The prediction contract would settle Yes in that scenario. Its near-99¢ quote measures confidence in a close above $83; it says nothing directly about the return available to someone buying after trading begins. Separate opening- and closing-price markets do not, by themselves, establish the probability of a gain between those two moments.
The $26 billion outside the IPO contract
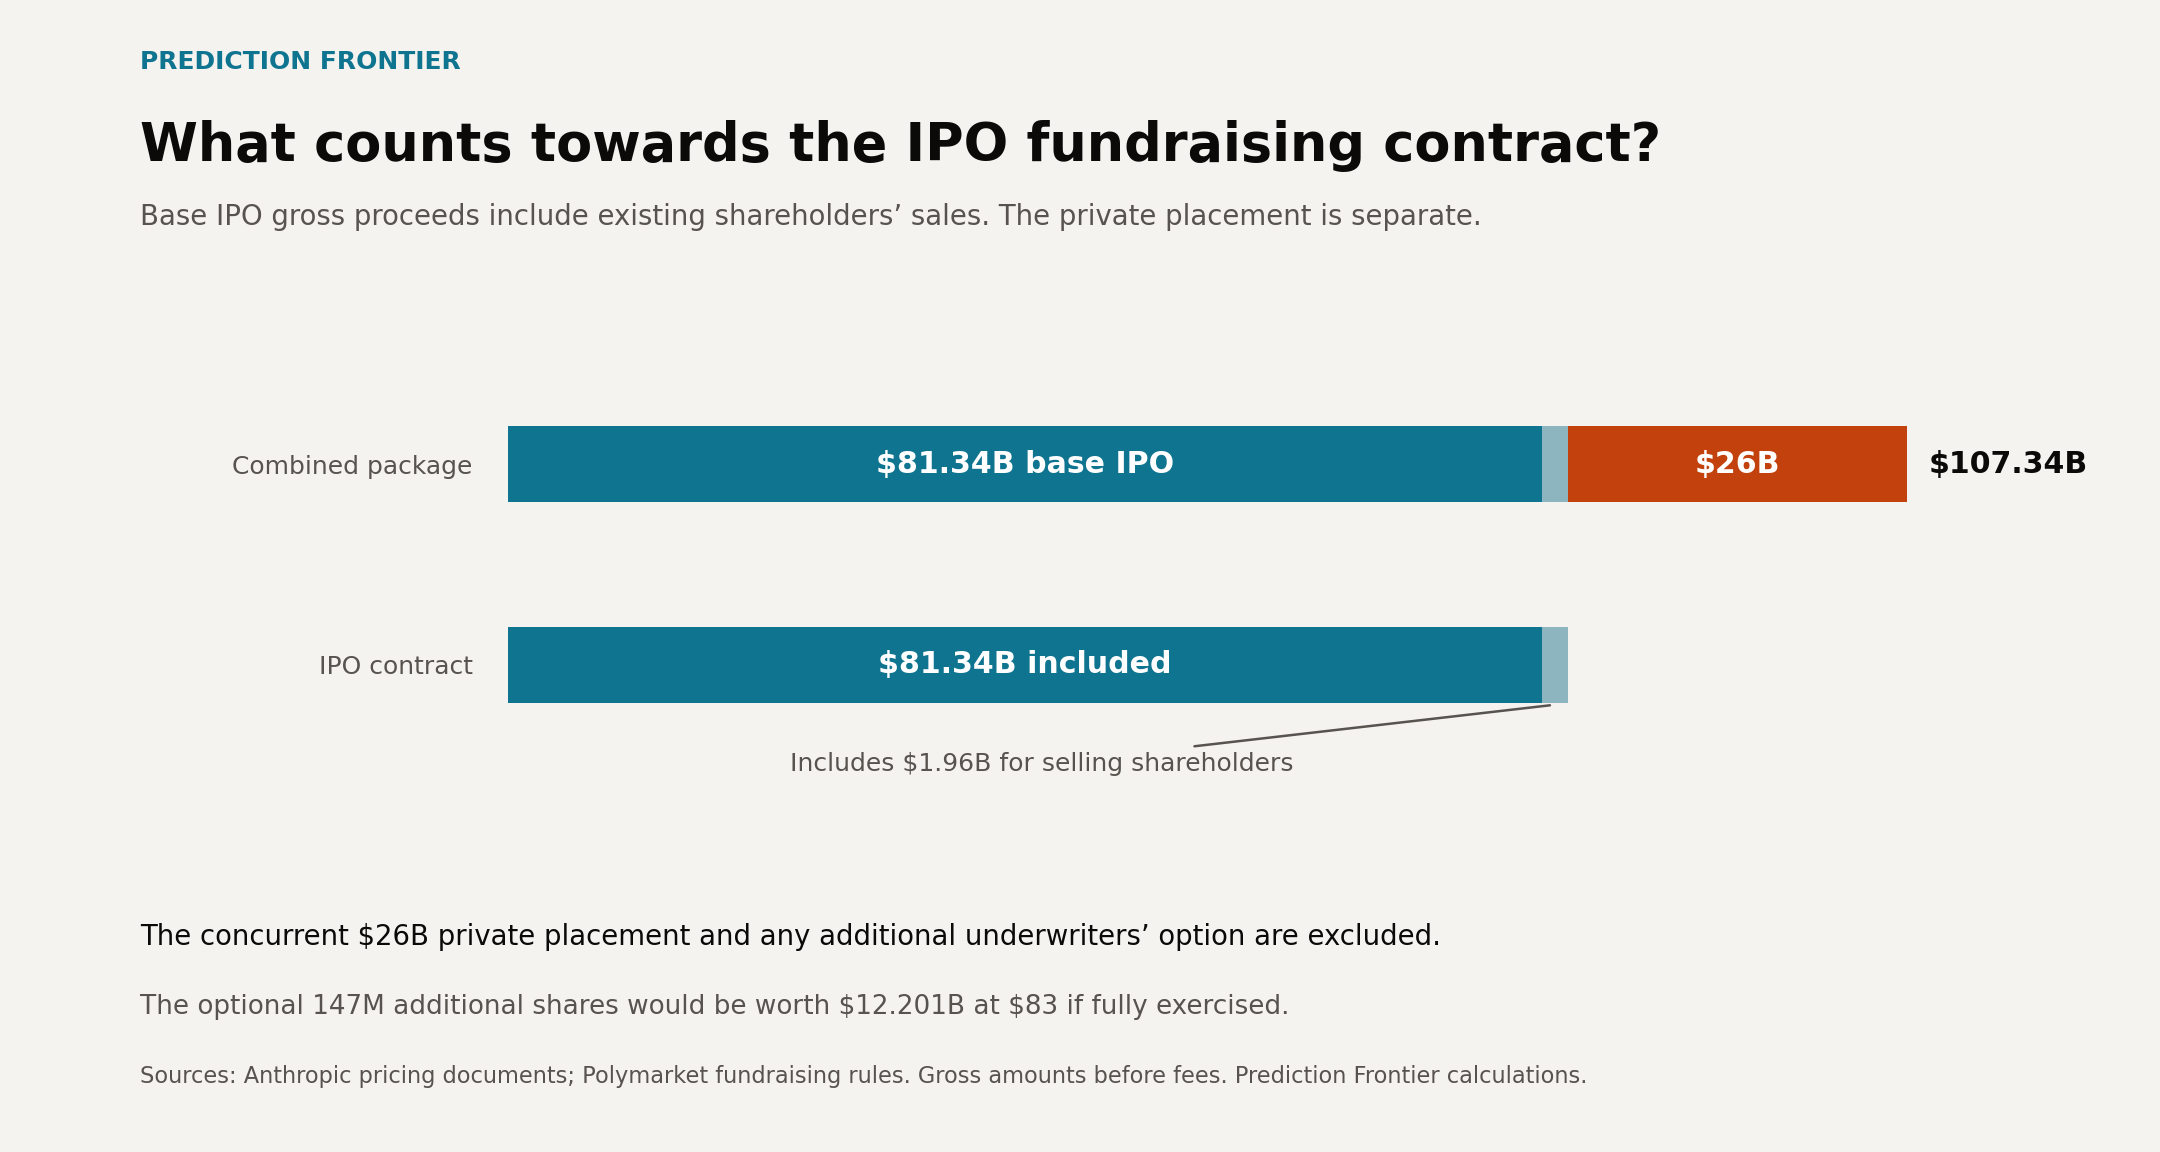
The fundraising markets also require a choice of what to count. Anthropic’s base IPO consists of 980 million shares at $83, producing $81.34 billion in gross proceeds. The pricing document lists a further $26 billion private placement alongside the offering. Combined, the two transactions amount to $107.34 billion before fees.
Polymarket’s IPO fundraising contract explicitly excludes the concurrent private placement. Its $75–$85 billion outcome was quoted at 99.7–99.8¢ in the same snapshot, consistent with the $81.34 billion base offering.
| Measure | Gross amount | Fundraising contract treatment |
|---|---|---|
| Base IPO | $81.34 billion | Included |
| Concurrent private placement | $26 billion | Excluded |
| Combined package | $107.34 billion | Only the base IPO counts |
| Additional underwriters’ option, if fully exercised | $12.201 billion | Excluded |
| Selling-stockholder proceeds within the base IPO | $1.962837618 billion | Included within $81.34 billion, not an additional amount |
The contract also excludes the additional 147 million shares available through the underwriters’ option. At $83, that option would be worth $12.201 billion if exercised in full.
It does count the 23,648,646 shares sold by existing stockholders inside the base offering. Those sales amount to approximately $1.96 billion, which Anthropic does not receive. The company’s own 956,351,354-share sale accounts for about $79.38 billion gross. A market asking how much the IPO raises can include money paid to existing holders while excluding a large private placement that funds the company.
Method. Prediction Frontier used Anthropic’s final 424B4 prospectus, its pricing announcement and pricing free-writing prospectus, plus Polymarket’s published rules and public API responses. Quotes were captured on 19 November 2026 at 11:44 UTC, before the scheduled Nasdaq debut. Share-price translations use 13,219,642,274 base Class A and Class N shares and exclude the underwriters’ option and subsequent share-count changes. The $100 close and $105 opening trade are hypothetical. Returns exclude costs, and proceeds are gross before fees.
Related reading: Three numbers behind GTA 6’s prediction markets.
Related reading
- Three numbers behind GTA 6’s prediction markets
Market Intelligence ·
- Polymarket says revenue run rate tops $1.8 billion, CNBC reports
Finance ·
- How Genius Sports earns from prediction markets before and after a trade
Market Intelligence ·